The 13-Week Cash-Flow Forecast Every Ecommerce Brand Should Build Before Scaling
- Topic
- Growth
- Source
- Ecommerce Fastlane
- Published
This summary was written by ShopDigest AI from Ecommerce Fastlane’s report, by Steve Hutt. Read the full story ↗
A 13-week cash-flow forecast helps ecommerce operators see whether usable cash will cover payroll, inventory, ads, taxes, refunds, and debt in each coming
Overview
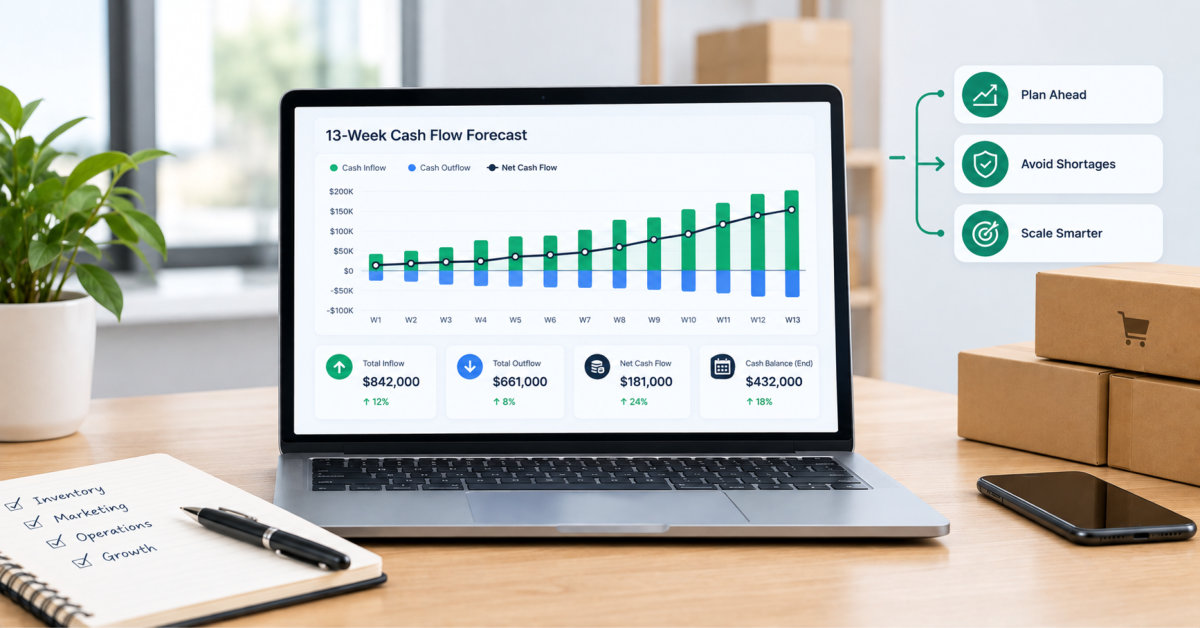
A 13-week cash-flow forecast helps ecommerce operators see whether usable cash will cover payroll, inventory, ads, taxes, refunds, and debt in each coming week. It protects growth by exposing timing gaps before the bank balance forces reactive decisions. The forecast is built from cleared bank balances, payout calendars, and scheduled outflows, not from accounting profit.
Key Details
- Start with usable cash: subtract tax reserves, committed supplier payments, and refund buffers from the bank balance.
- Forecast cash receipts from payout calendars per channel (own store, Amazon, wholesale), not from gross sales.
- Map every material outflow to the week it is paid, including inventory deposits, freight, payroll, ads, and taxes.
- Inventory purchase orders can create 3–4 separate cash events before the first unit sells.
- Maintain the forecast on a rolling basis: replace each week with actuals and add a new Week 13.
Why It Matters
Revenue, profit, and cash are different things; a brand can report its best sales month and still miss payroll. Growth amplifies timing gaps because inventory deposits leave the bank months before stock produces revenue. A 13-week forecast turns these timing differences into a weekly operating tool that supports decisions about inventory, marketing, collections, supplier terms, or financing.
Frequently asked questions
What is a 13-week cash-flow forecast for ecommerce?
A 13-week cash-flow forecast is a rolling weekly tool that projects usable cash balances for the next quarter. It shows whether cash will cover payroll, inventory, ads, taxes, refunds, and debt in each coming week, exposing timing gaps before they force reactive decisions.
How do I calculate usable opening cash for a cash-flow forecast?
Start with cleared balances in operating accounts and subtract restricted, reserved, or already committed funds. For example, a $120,000 bank balance might include $28,000 for sales tax, $15,000 for a supplier payment, and $7,000 as a refund buffer, leaving about $70,000 of usable operating cash.
Why use 13 weeks instead of a monthly forecast?
Thirteen weeks is roughly one quarter—long enough to expose an inventory purchase, seasonal campaign, or supplier payment before it becomes urgent, but short enough to update with credible information. Monthly forecasts can hide dangerous timing, such as dropping below a safe minimum between a supplier deposit and a payout.
How should I forecast cash receipts from sales?
Do not copy projected gross sales into the cash-in row. Instead, forecast the amounts and weeks money is expected to become available, accounting for payment processing, marketplace settlement schedules, refunds, chargebacks, reserves, discounts, and gift-card redemptions. Separate dependable receipts from optimistic ones.
What cash outflows should be included in a 13-week forecast?
Include inventory deposits and balances, freight and duties, fulfillment and storage, payroll and contractors, advertising, software, rent and overhead, sales tax and income-tax payments, refunds, debt or financing obligations, and planned capital expenditure. Each expense should appear in the week cash actually leaves the account.
How does inventory create multiple cash events in a forecast?
A single purchase order may create three or four separate cash events: the deposit, the balance due, the freight payment, and possibly duties. These can occur weeks or months before the first unit is sold, creating a cash trough that the forecast makes visible.
When should financing be used versus masking a structural problem?
Financing is a sensible timing bridge when cash gaps are temporary, such as between an inventory deposit and launch revenue. It masks a structural problem when the business model consistently cannot meet obligations from operating cash flow, indicating a deeper issue with margins, pricing, or cost structure.
